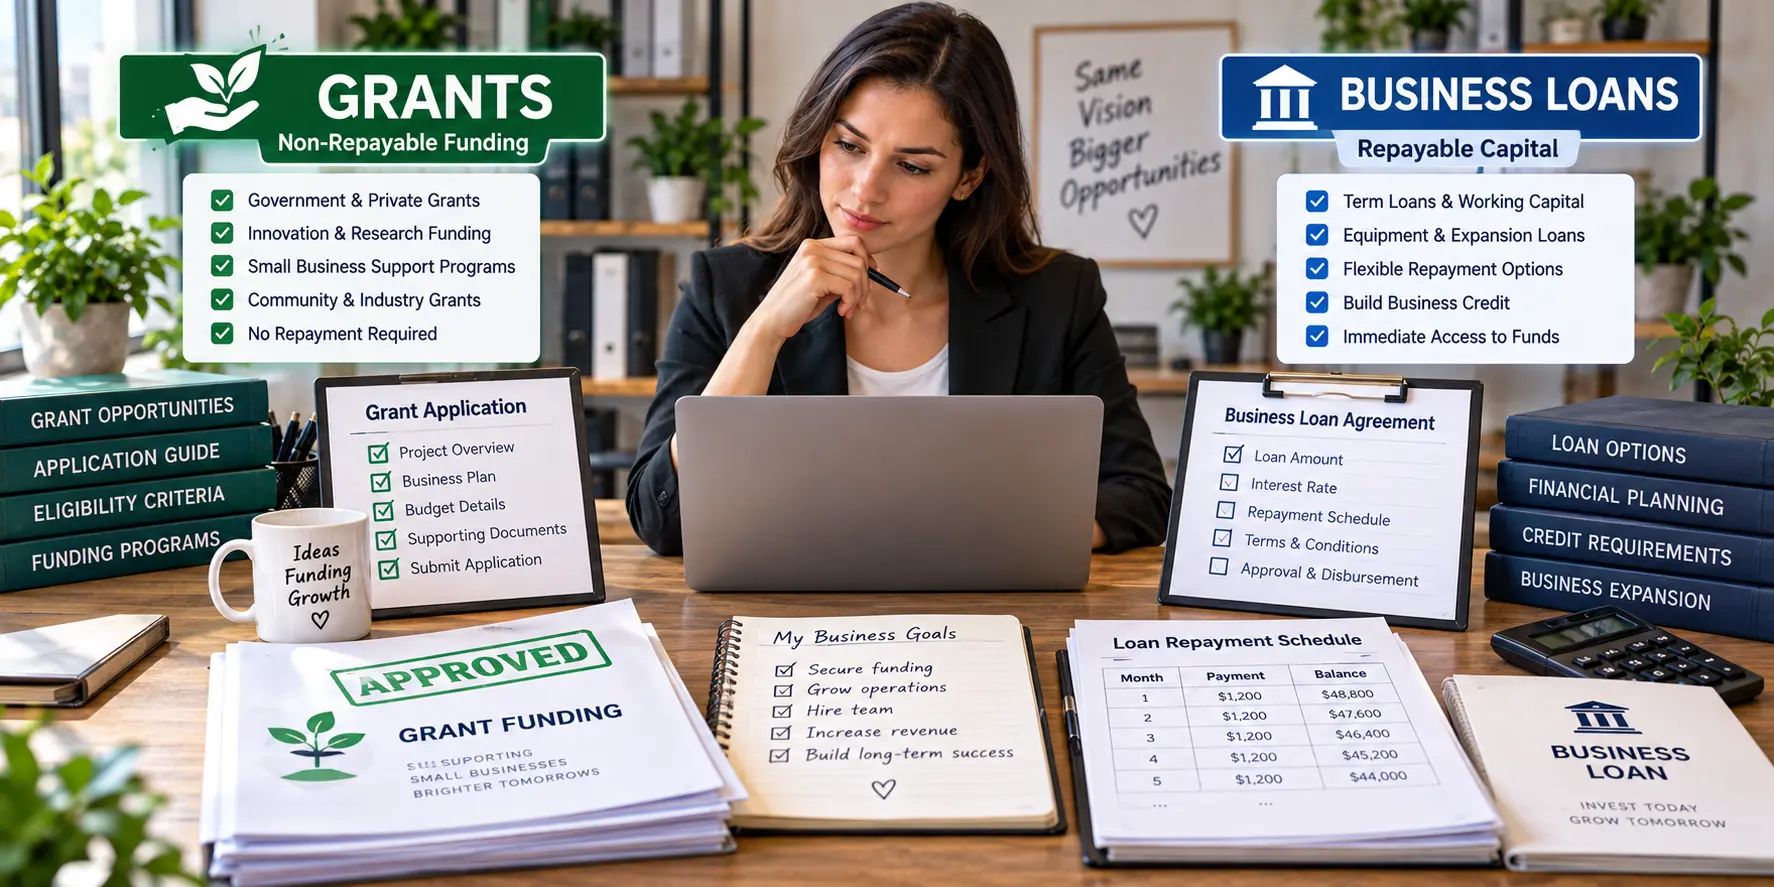
The main difference between a business grant vs business loan is repayment. A business loan generally provides borrowed money that must be repaid according to agreed terms, usually with interest or other financing costs. A grant generally provides funding that does not require conventional repayment when the recipient follows the program’s conditions. However, grants often have specific eligibility rules, permitted uses, application requirements, and reporting obligations.
For small-business owners considering outside funding, understanding these differences can help determine which opportunities are worth investigating.
What Is a Business Grant?
A business grant is funding provided through a grant program for an eligible purpose or recipient.
Programs may be offered by government agencies, nonprofit organizations, foundations, corporations, industry groups, or other entities. Each program establishes its own eligibility requirements and application process.
Grant criteria may consider factors such as location, industry, business activities, project purpose, company size, ownership characteristics, or how the money will be used.
Unlike a conventional loan, qualifying grant funds generally do not create a standard repayment schedule. However, that does not mean grant money is unrestricted.
Recipients may need to use funds only for approved purposes, retain supporting documentation, meet deadlines, or provide progress and expenditure information.
What Is a Business Loan?
A business loan is borrowed capital that a company agrees to repay under defined financing terms.
Depending on the financing arrangement, those terms can include the principal amount, interest rate, repayment schedule, fees, collateral requirements, and other conditions.
Business financing can take different forms. Examples may include term loans, lines of credit, equipment financing, and other commercial lending products.
Lenders commonly evaluate whether an applicant appears capable of repaying the debt. The specific evaluation can depend on the lender and product and may involve business revenue, financial statements, cash flow, credit history, operating history, collateral, or personal guarantees.
Business Grant vs Business Loan: Key Differences
Although both can provide capital, grants and loans operate differently.
Repayment
A loan creates a repayment obligation according to its contract.
A grant generally does not require conventional repayment when all program conditions are satisfied. However, failure to follow grant requirements can potentially create problems, so recipients should understand the terms before accepting funds.
Availability
Business loans are offered through many banks, credit unions, online lenders, and other financing providers.
Grant opportunities tend to be connected to specific programs and purposes. A business must usually find a program for which it qualifies rather than simply requesting a general-purpose grant.
Eligibility
Lenders focus heavily on creditworthiness and repayment capacity.
Grant providers may use a broader set of program-specific eligibility criteria. A financially healthy business can still be ineligible for a grant if it does not meet the program’s requirements.
Use of Funds
Some loans allow relatively broad business use, while others are tied to a specific purpose.
Grants can also restrict how money is spent. A program intended for technology adoption, training, research, expansion, or another defined purpose may require the recipient to use funding accordingly.
Are Business Grants Really Free Money?
Describing grants simply as “free money” can be misleading.
While qualifying grants generally do not operate like repayable loans, applying can require significant time and documentation. Recipients may also have obligations regarding how the funds are used and reported.
A grant application might require a business plan, project description, budget, financial information, eligibility documentation, or explanation of the expected use of funds.
Competitive programs may receive more eligible applications than they can fund.
For that reason, a grant should be evaluated as a structured funding opportunity rather than guaranteed money without conditions.
When Might a Business Loan Make More Sense?
A loan may be more practical when a business has a defined funding need and can reasonably support repayment.
For example, a company might need financing for equipment, inventory, working capital, expansion, or another commercial purpose.
The important question is whether the expected benefit justifies the financing cost and repayment obligation.
Owners researching funding alongside business credit, cash flow, banking, and financial planning can check here through GrowBizLab for broader small-business information that can support their research.
Before accepting financing, owners should understand the total borrowing cost, repayment schedule, applicable fees, and consequences of guarantees or collateral requirements.
When Might a Grant Be Worth Pursuing?
A grant may be worth investigating when a business clearly fits a program’s eligibility criteria and the funded purpose aligns with something the company already plans to do.
For example, if a qualifying program supports a specific type of training, innovation, community project, or business development activity that matches the company’s plans, applying may be reasonable.
Owners should compare the potential funding with the time required to prepare the application and satisfy any ongoing requirements.
Applying indiscriminately to unrelated programs can consume time that could be spent on more suitable financing opportunities or business operations.
Can a Business Use Both Grants and Loans?
Potentially, yes.
Grants and loans are not necessarily mutually exclusive. A business may qualify for a grant for one eligible project while using financing for a different purpose.
However, owners should check the conditions attached to each funding source.
A grant program may restrict how awarded money is used, while a lender may impose its own requirements. Accurate records are important when different funding sources support different activities.
Compare Funding With the Business’s Actual Need
Before searching for money, define why the business needs capital.
Is the company purchasing equipment? Managing a temporary cash-flow gap? Expanding operations? Developing a new product? Hiring employees? Funding a specific eligible project?
The answer can narrow the available options.
Owners should also estimate how much money is actually required. Borrowing significantly more than necessary can increase financing costs, while pursuing a small grant that does not meaningfully support the project may not justify a complicated application.
Prepare Before Applying
Whether pursuing a grant or a loan, organized business records can make the process easier.
Relevant materials may include financial statements, bank records, tax information, revenue history, budgets, business registration documents, project plans, and explanations of how funds will be used.
The exact requirements depend on the provider.
Owners should rely on official program or lender information when evaluating eligibility and application requirements, particularly because funding programs and financing terms can change.
Choosing between a business grant and a business loan ultimately depends on the company’s purpose, eligibility, timing, financial position, and ability to meet the conditions attached to the funding. Understanding repayment requirements, restrictions, application demands, and financing costs allows owners to compare opportunities based on how they actually fit the business rather than simply choosing whichever option sounds less expensive.